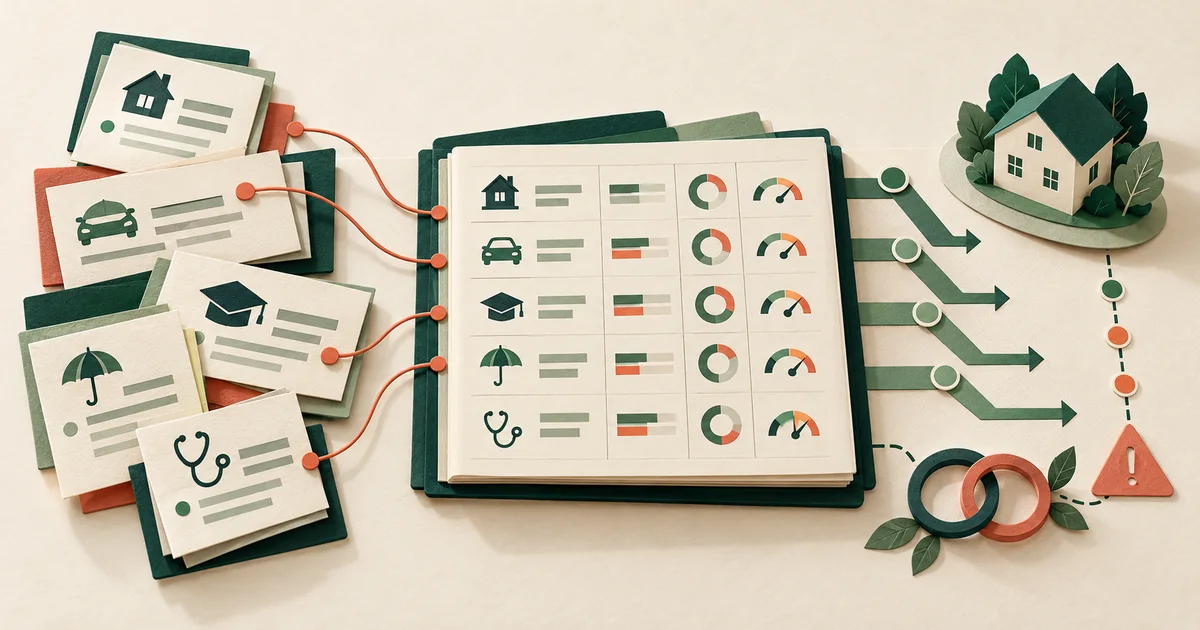
Private agreements may not change creditor rights
A family promise, separation agreement, business sale, or transfer of possession may not release a borrower or guarantor. Look for creditor-approved evidence and obtain advice where rights are disputed.
Roles that look similar but create different exposure
- Name the exact contractual role
- Do not confuse access with liability
- Track collateral and recourse
- Keep evidence of releases and closure
Separate the roles
A joint borrower generally signs for and owes the debt. A co-signer promises repayment if the primary borrower does not. A guarantor’s exposure depends on the guarantee. An authorized user may be permitted to use an account without being contractually liable, but terms and jurisdictions matter.
For each obligation, create columns for borrower, co-borrower, co-signer, guarantor, authorized user, property owner, payment source, and statement recipient. Fill a role only when supported by the agreement or institution record.
This matrix exposes arrangements where one person pays but is not an owner, owns collateral but does not receive statements, or has account access without contractual liability. Those distinctions matter during conflict or incapacity.
Inventory evidence, not assumptions
Keep the signed agreement location, lender contact, current status, notice address, collateral owner, and any release conditions. Do not infer liability from who makes the monthly payment.
Read the signature block, definitions, and later amendments together. Marketing labels and online account access can hide the contractual role, while a refinance or modification may have changed the original arrangement. Record the document date and the page or section supporting each role so another reviewer can retrace the conclusion instead of accepting a label without evidence.
Shared obligations also belong in the continuity information described by the continuity checklist for executors. For the current household view, place each contractual role beside its balance and APR in the private debt inventory tool.
Read the role shown in the contract
People may call a debt shared. The contract may give each person a different job. The signed terms show who must pay.
- Copy the role from the contract.
- Write who owns the pledged property.
- Write who gets bills and notices.
Practical tip: Do not write “shared debt” if the contract says something else.
Map the contract before testing change scenarios
- Collect the signed agreementUse the contract and current statement to identify parties and roles.
- Map exposureRecord balance, payment, collateral, guaranty scope, and whose credit or assets may be affected.
- Test change scenariosAsk what happens after separation, death, sale, refinance, default, or business closure.
- Confirm any releaseDo not assume a private agreement removes a borrower or guarantor without creditor acceptance.
Stress-test the relationship
Ask what happens if one person dies, becomes disabled, loses income, or stops cooperating. Check whether automatic payments and online access depend on only one person. Identify insurance or reserves intended to protect the obligation.
Add a communication map beside the financial exposure. Note who receives statements, default notices, tax forms, insurance notices, and title documents, plus whether contact details are current. A person can face serious exposure while receiving no routine mail. The mismatch is an action item even when every payment is currently on time.
Know when to get advice
Divorce, business guarantees, estate administration, and disputed signatures need legal advice. A private inventory can surface the exposure early, but it is not a legal conclusion.
Selling collateral, refinancing, creditor-approved assumption, account closure, or a written release can change exposure. A divorce decree, family promise, business sale, or transfer of possession may not by itself change a creditor’s contract rights.
Keep payoff, release, lien, closure, and title evidence together and verify the next statement or public record where appropriate. Seek qualified advice for guarantees, marital property, estates, and cross-border obligations.
Evidence for each person, asset, and exit
- Contractual role
- Signed agreement
- Payment responsibility
- Collateral owner
- Notice recipient
- Release terms
Place shared obligations in the household debt map
Record the contractual role, payment, collateral, and source agreement. Use calculations only after the exposure and urgent risks are understood.
- Use a private debt inventory and APR comparison toolCalculate total debt, required monthly payments, weighted APR, and an illustrative highest-rate-first comparison in your browser.
Questions about liability, access, and release
Is an authorized user responsible for the debt?
Roles and laws vary; do not infer liability from card access. Check the agreement and obtain qualified advice if disputed.
Does divorce remove a co-borrower?
Do not assume so. A creditor agreement and a court order can address different relationships.
How can a guarantor know exposure ended?
Obtain written release, payoff, closure, or other authoritative evidence applicable to the agreement.
Consumer guidance for co-signed obligations
These first-party government, regulator, or established professional sources support the specific task above. They are provided for verification and do not imply endorsement.