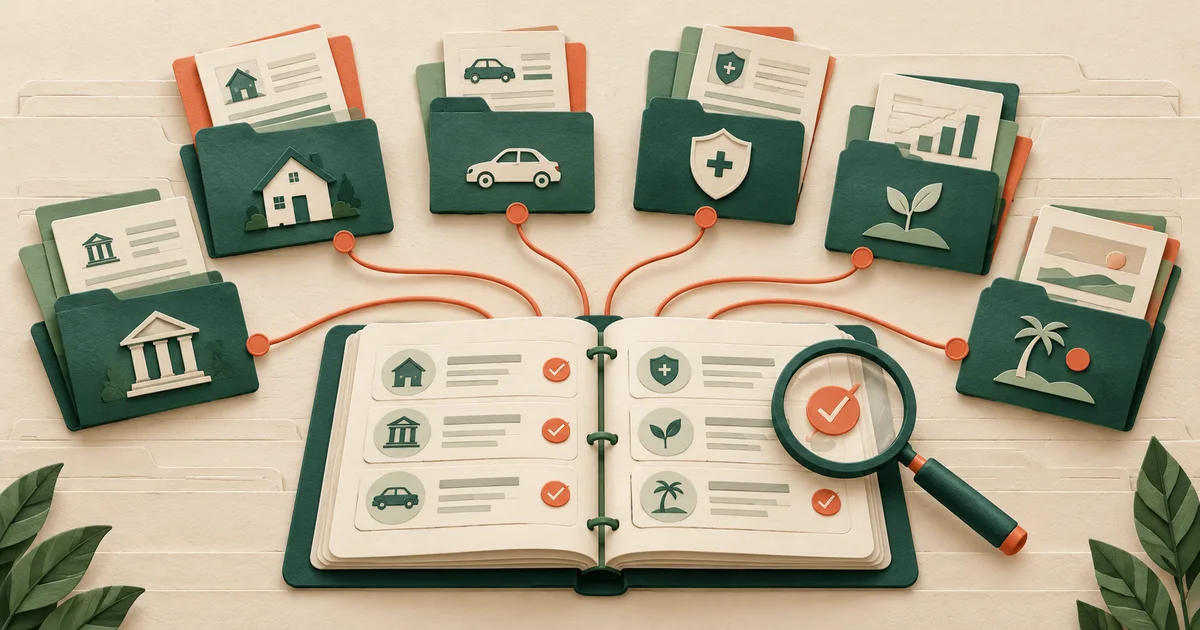
An account inventory answers a deceptively hard question: where does your money live? The useful version includes ownership, purpose, access instructions, beneficiaries, and a safe pointer to the original record - Not credentials.
Record the institution, account type, owner, and a masked identifier.
Explain
Note what the account is for and who would need to know it exists.
Point
Record where the authoritative statement or access instruction is kept.
Guides in this collection
Begin with the safe account fields, then work outward: search for missing accounts, confirm beneficiary records, organize the source files, and reconcile old retirement plans.
A durable inventory is a small operating system for the household: one index, clear ownership, safe pointers to source records, and a review rhythm that survives busy months.
A filing system should make the current authoritative record easy to find while keeping obsolete copies, duplicates, and exposed personal data under control.
Retirement assets are easy to fragment across employers and institutions. A complete inventory connects each plan to its owner, administrator, beneficiary record, statements, and unresolved decisions.
A useful account inventory identifies the institution, legal owner, household purpose, masked reference, authoritative record, beneficiary status, and review date - Without storing access secrets.
Start with ownership and purpose
List deposit, investment, retirement, payment, education, and health-savings accounts by legal owner. Add a plain-language purpose such as household bills, emergency savings, or retirement income. Ownership and purpose explain who controls the account and what would be disrupted if it were overlooked.
Make records findable without copying secrets
Use a masked reference and point to the latest statement, beneficiary confirmation, or secure access instructions. Keep passwords, recovery codes, full account numbers, and identity documents out of the inventory. The goal is discovery and coordination, not enough information to impersonate the owner.
Which institution holds the account, and who legally owns it?
What household job does the account perform?
Where is the current statement or authoritative record?
Has the beneficiary or transfer instruction been verified with the institution?
Common questions about account records
Short answers establish the safe starting point; the linked guides handle the full task.
What is the safest way to list a financial account?
Record the institution, account type, owner, purpose, masked reference, and location of the current statement. Keep passwords, PINs, recovery codes, and full account numbers out of the inventory.
How often should an account inventory be reviewed?
Review it after an account opens, closes, changes owner, moves to another institution, or receives a new beneficiary instruction. A scheduled annual check can catch changes that did not trigger an immediate update.
Does an account inventory replace statements or beneficiary forms?
No. It is a discovery map. Statements, institution records, and current beneficiary confirmations remain the authoritative sources.