Rules that keep one household index maintainable
- Index records; do not duplicate secrets
- Separate everyday access from emergency handoff
- Use one naming rule across every category
- Review changes, not every document from scratch
Design the inventory around questions
The inventory should answer what exists, who owns or controls it, what it is for, where the authoritative record lives, and what event should trigger action. Those questions work across bank accounts, loans, policies, and estate documents, which is why a common index is more useful than four unrelated lists.
Add category-specific fields only after the common fields. An account may need a beneficiary status; a debt may need collateral; a policy may need a deductible; a document may need a signed-original location. This layered design keeps the system understandable without flattening important differences.
Components of the working system
- Master category index
- Owner or responsible person
- Purpose
- Masked reference
- Source-record location
- Recurring income and bills
- Key contacts and roles
- Review trigger
- Change log
Choose storage without creating a credential vault
A paper binder, encrypted file, or reputable secure vault can all work if the household can actually maintain and recover them. The index should use masked references and location pointers. Authentication secrets belong in a separate password-management or sealed-instruction process appropriate to the household.
Avoid linking convenience to unnecessary exposure. A direct hyperlink to an institution can be useful; a saved username beside the link may not be. Record enough to distinguish two similar accounts, but not enough for a stranger holding the inventory to impersonate an owner.
The inventory works best when its source records follow a consistent financial document organization method. Build the actual household index in the private household inventory builder using masked identifiers and record pointers.
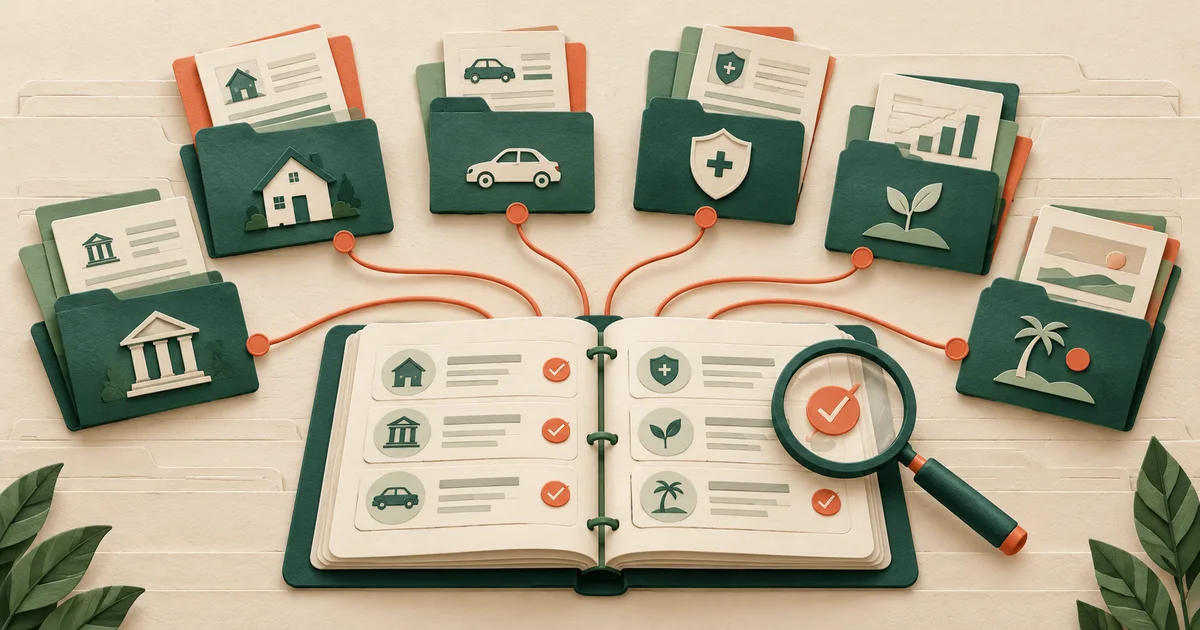
One map connects four household systems
Accounts hold value. Debts create duties. Insurance protects against loss. Estate records help other people act when needed.
- Give every item an owner and purpose.
- Point every item to a source record.
- Give every open question a next action.
Practical tip: Build one category at a time. A small current inventory is better than a large stale one.
Set up the source of truth and its backup
- Choose the boundaryInclude accounts, obligations, policies, critical documents, and contacts. Exclude passwords and full identifiers.
- Create the master indexUse the same core fields for every item so gaps become visible.
- Connect source recordsPoint to statements, declarations, signed originals, or secure vault folders without copying sensitive contents.
- Set the handoffName who maintains the index, who can locate it in an emergency, and when it will be reviewed.
Assign responsibility and backup
One person should be responsible for routine updates, but a one-person system is fragile. Choose a backup who knows the inventory exists, where the access instructions are, and whom to contact. This does not automatically grant legal authority; it creates discoverability.
Record professional and institutional contacts by role rather than relying on memory: plan administrator, insurance claims number, attorney office, tax preparer, or benefits desk. Confirm that a contact is still current during review instead of assuming an old business card remains useful.
Run a change-based review
A full annual review is useful, but event triggers catch important changes sooner. Review after a move, job change, new account, closed loan, marriage, divorce, birth, death, major purchase, new policy, or executed estate document.
Keep a short change log with the date, affected record, and action taken. The log prevents repeated work and makes silence meaningful: if the index says an account was closed, a future reviewer will not waste time searching for a missing statement.
Start the master index on this device
Use the financial organizer for the cross-category map and the net-worth tool for a separate dated calculation. Neither tool connects to financial institutions.
- Use a private financial inventory organizerBuild a clear index of what exists, who owns it, and where the authoritative record lives. Entries remain in this browser unless you export them.
- Calculate your net worth with a private calculatorA private, line-by-line snapshot with totals and a debt-to-asset ratio you can understand.
Add the household continuity layer
An account and document list can still leave a household unable to operate. Add recurring bills, recurring income, benefit payments, service providers, autopay sources, renewal dates, and the contacts connected to urgent financial tasks. Record the purpose of each item so another person can tell which payment keeps housing, utilities, insurance, care, or transport running.
Keep contact, authority, and access separate. A tax preparer, insurance agent, plan administrator, attorney, property manager, or trusted relative may know important facts without having authority to act. Record the role and a verified contact route, then point to the document that establishes authority when one exists.
Discoverability is different from authority
A trusted person can know where records and instructions are without having permission to access accounts or act for someone else. Record authority only from the controlling source.
Questions about balances, copies, and trusted people
Should the inventory include current balances?
Only if balances help the household task. Mark each amount with an as-of date and treat the institution statement as authoritative.
Should recurring bills and income be included?
Yes when they matter to household continuity. Record the provider or payer, purpose, schedule, payment or deposit source, and where the current record can be found.
Should both partners keep separate copies?
Redundancy can help, but uncontrolled copies drift and increase exposure. Designate one source of truth and a deliberate backup process.
Does a trusted person need legal authority?
Knowing where records are is different from having authority to act. Powers depend on contracts and law; ask a qualified professional about the household’s situation.
Preparedness sources behind the system
These first-party government, regulator, or established professional sources support the specific task above. They are provided for verification and do not imply endorsement.